Frequently asked questions (FAQs)
This set of FAQs is only for members of the MAS Retirement Savings Scheme (RSS) who have received an email communication from MAS in the week beginning 2 March 2026 in relation to a historical tax reporting error on their RSS account. You can refer this page to your tax adviser/accountant.
To make sure you can still update the PIR for any of the affected tax years if needed, we suggest you contact Inland Revenue before 31 March 2026.
If you have any questions regarding the information provided below or in the email communication, we’re here to help. Call us on +64 4 832 3796 or 0800 800 627, or email us at lifeandinvestmentcentre@mas.co.nz.
Understanding the reporting error
What happened and why did I receive an email?
There’s been an error in the way MAS reported certain information to Inland Revenue for your MAS Retirement Savings Scheme (RSS) joint account that may have affected the PIE tax you paid for the tax years between 1 April 2020 - 31 March 2024.
In 2020, there were changes in the New Zealand Portfolio Investment Entity (PIE) information reporting rules that affected RSS joint accounts. This meant we had to start reporting certain information, including the IRD number, for both joint account holders if we held that information. Previously, we were only required to report this information for the primary account holder – the RSS joint account holder with the highest PIR.
The changes were made to enable PIE income to be automatically split and applied in Inland Revenue’s system between joint account holders of PIEs like RSS. PIEs must deduct tax at the highest prescribed investor rate (PIR) and therefore some joint holders may be over-taxed with Inland Revenue
However, due to a reporting error, our system only reported the IRD number for the primary account holder, between 1 April 2020 and 31 March 2024. This means you may be entitled to a tax refund if your secondary account holder’s PIR was lower than the primary account holder’s.
The secondary account holder will need to check their PIR and their Inland Revenue records to see whether their PIE tax was incorrect for one or more of the tax years from 1 April 2020 to 31 March 2024.
Why wasn't the PIR for both account holders used?
For a joint account, the tax rules require us to calculate PIE tax for that account using only one PIR.
The PIR used should be the highest one amongst the joint holders of that account.
Does this issue affect my other MAS Investment accounts?
No, other investment accounts you may hold with MAS are not impacted by this error — only RSS.
Will this issue impact any other tax types (e.g., income tax, Working for Families, student loan repayments)?
No, we do not expect this matter to impact any other tax types that are relevant to you.
Does this issue affect the primary account holder as well?
We do not expect this issue to also affect the primary account holder.
The reporting error only affected secondary account holders on jointly held accounts. We believe that the primary account holder’s information was reported correctly.
Does this error affect how much money is currently in my RSS investment with MAS?
We do not believe that it should affect the value of your RSS investment. This reporting issue only relates to tax information provided to Inland Revenue for the tax years between 1 April 2020 to 31 March 2024. Any change in PIE tax resulting from the PIR used being different to your correct PIR, would ordinarily occur in your Inland Revenue account not in your RSS account. It should not affect your investment balance, fund performance, or unit holdings.
Will this error affect my future PIR settings?
We would not typically expect this to affect your future PIR settings. Future PIRs for your joint RSS account will continue to be based on the highest PIR of the joint account holders, with reference to the PIR selected and the information held in our system (or the PIR that Inland Revenue has asked us to use). You can update your joint account PIR with us at any time by contacting us.
Actions you need to take
What do I need to do?
The secondary joint account holder will need to check their PIR and their Inland Revenue records to see whether their PIE tax was incorrect for one or more of the tax years from 1 April 2020 to 31 March 2024.
The steps below will help you see if any correction is needed for past tax years.
- Check Inland Revenue’s view of the correct PIR for the secondary joint account holder for each of the financial years between FY2021 and FY2024. The easiest way to do this is for the secondary joint account holder to access their myIR account and go to 'View Your PIR' (Income Tax > More > My Details) then chose the tax year they want to check e.g. 1 April 2020 – 31 March 2021 etc.
- If you believe that the secondary joint account holder’s PIR was lower than the primary joint account holder's PIR in any tax year between 1 April 2020 and 31 March 2024, you will need to contact Inland Revenue directly. You can contact Inland Revenue using the ‘Communicating with IR' secure messaging option within myIR or call them on 0800 227 774. You will need to provide Inland Revenue with at least your name and IRD number. You can tell them:
- 'I believe my PIR for the 20XX tax year is XX%, based on what I see in my myIR account,' and
- 'I have been advised that the PIR used to calculate my PIE tax for my investment in the MAS Retirement Savings Scheme for that year was XX%,' and
- 'Please review and reassess the PIE tax position for that year.'
To make sure you can still update the PIR for any of the affected tax years if needed, we suggest you contact Inland Revenue before 31 March 2026.
What do I need to do if the PIR I see in myIR matches the PIR that you stated in the email was applied for each tax year?
If the PIR shown in your (secondary joint account holder's) myIR account matches the PIR used to calculate your RSS PIE tax for each tax year, then you do not need to take any further action.
Why can’t MAS fix it for me or provide me with tax advice?
We cannot see your personal tax information held by Inland Revenue and, due to privacy rules, we cannot contact Inland Revenue or make changes on your behalf. Because of this, we cannot tell you what your PIR should have been or what action you should take based on your individual circumstances.
We recommend speaking with Inland Revenue or contacting a qualified tax adviser if you need guidance beyond the information provided in our email communication to you and these supporting FAQs.
What happens if I was taxed at a higher PIR than I should have?
If Inland Revenue reviews your information and confirms that a lower PIR should have applied to one or more of the affected years, you have been taxed more than necessary on your RSS PIE income for that year. Inland Revenue should then refund that excess tax to you (or apply it to any other outstanding tax liabilities that you have) as part of your updated tax assessment. You should not need to take any further steps once the reassessment is complete.
When do I need to take action?
Inland Revenue allows you to amend a tax return for up to 4 years after the end of the tax year in which it was filed. For example, if your 2021 return was filed by the due date, you should be able to make changes to it until 31 March 2026.
To make sure you can still update any of the affected years if needed, we suggest checking your PIR details and then, if an amendment is required, contacting Inland Revenue before 31 March 2026.
What happens if I was taxed at a lower PIR than I should have?
If Inland Revenue reviews your information and confirms that a higher PIR should have applied to one or more of the affected years, it means you paid less tax on your RSS PIE income than you should have for that year. Inland Revenue will then likely include the difference (the shortfall) in your updated position and you will be liable to pay that amount.
Based on what we know, we do not expect this situation to be applicable to many affected members.
How long will it take for Inland Revenue to process a reassessment?
Timeframes vary, but Inland Revenue usually completes reassessments within a few weeks. You can monitor progress through your myIR account. If you call Inland Revenue, it may be done immediately.
When Inland Revenue completes a reassessment that results in any change, you should receive a notice advising that your tax assessment has been updated. This notice should confirm whether you:
- are due a refund, or
- have tax to pay, and the due date for any payment.
You should receive this notification in your myIR account (and/or by email or post if you have chosen those options). We expect that no further action should then be required unless Inland Revenue indicates otherwise or you consider the position is still incorrect.
Working out your PIR
What is a prescribed investor rate (PIR)?
A prescribed investor rate (PIR) is the tax rate applied to income you get from your investment in a multi-rate portfolio investment entity (PIE) e.g. the MAS Retirement Savings Scheme (RSS).
How is the PIR calculated?
Your PIR for a specific year is based on your taxable income and PIE income from the two tax years immediately before that year.
The table below shows the bands and PIR rates that applied for the years affected by this reporting error (the tax years between 1 April 2020 to 31 March 2024).
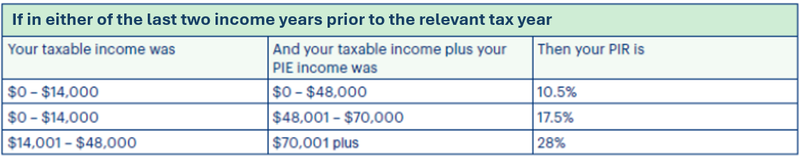
The following is an example of how the calculation works for the PIR for the 31 March 2023 tax year where the person had:
- Total taxable and PIE income from 1 April 2020 to 31 March 2021 of $50,000
- Total taxable and PIE income from 1 April 2021 to 31 March 2022 of $80,000
To work out your PIR for the 2023 tax year (1 April 2022 to 31 March 2023), Inland Revenue looks at both of the two previous tax years. The PIR that applies is the lower PIR of the two years. As such, based on the bands, the correct PIR is 17.5%.
What PIR was applied to my RSS PIE tax income?
The PIR applied to your RSS PIE tax income for each of the tax years from 1 April 2020 to 31 March 2024 is set out in the email you received from us. It will be the highest (primary account holder's) PIR.
Can I use Inland Revenue’s calculator to work out my correct PIR for this situation?
No. This is because the bands that determine what your PIR is changed from 1 April 2025 and, unfortunately, Inland Revenue’s current online PIR calculator only shows the PIRs from that date (not for the earlier years that may be affected by the reporting error).
The secondary joint account holder will need to check their PIR and their Inland Revenue records in their myIR account for the relevant text years as per 'What do I need to do?' FAQ.